Whole Life Insurance

Steady, Lifelong Protection You Can Count On

Whole life insurance offers coverage for your entire life, fixed premiums and cash value that grows at a guaranteed rate set by the policy. We explain how it works and compare options from A-rated financial companies.
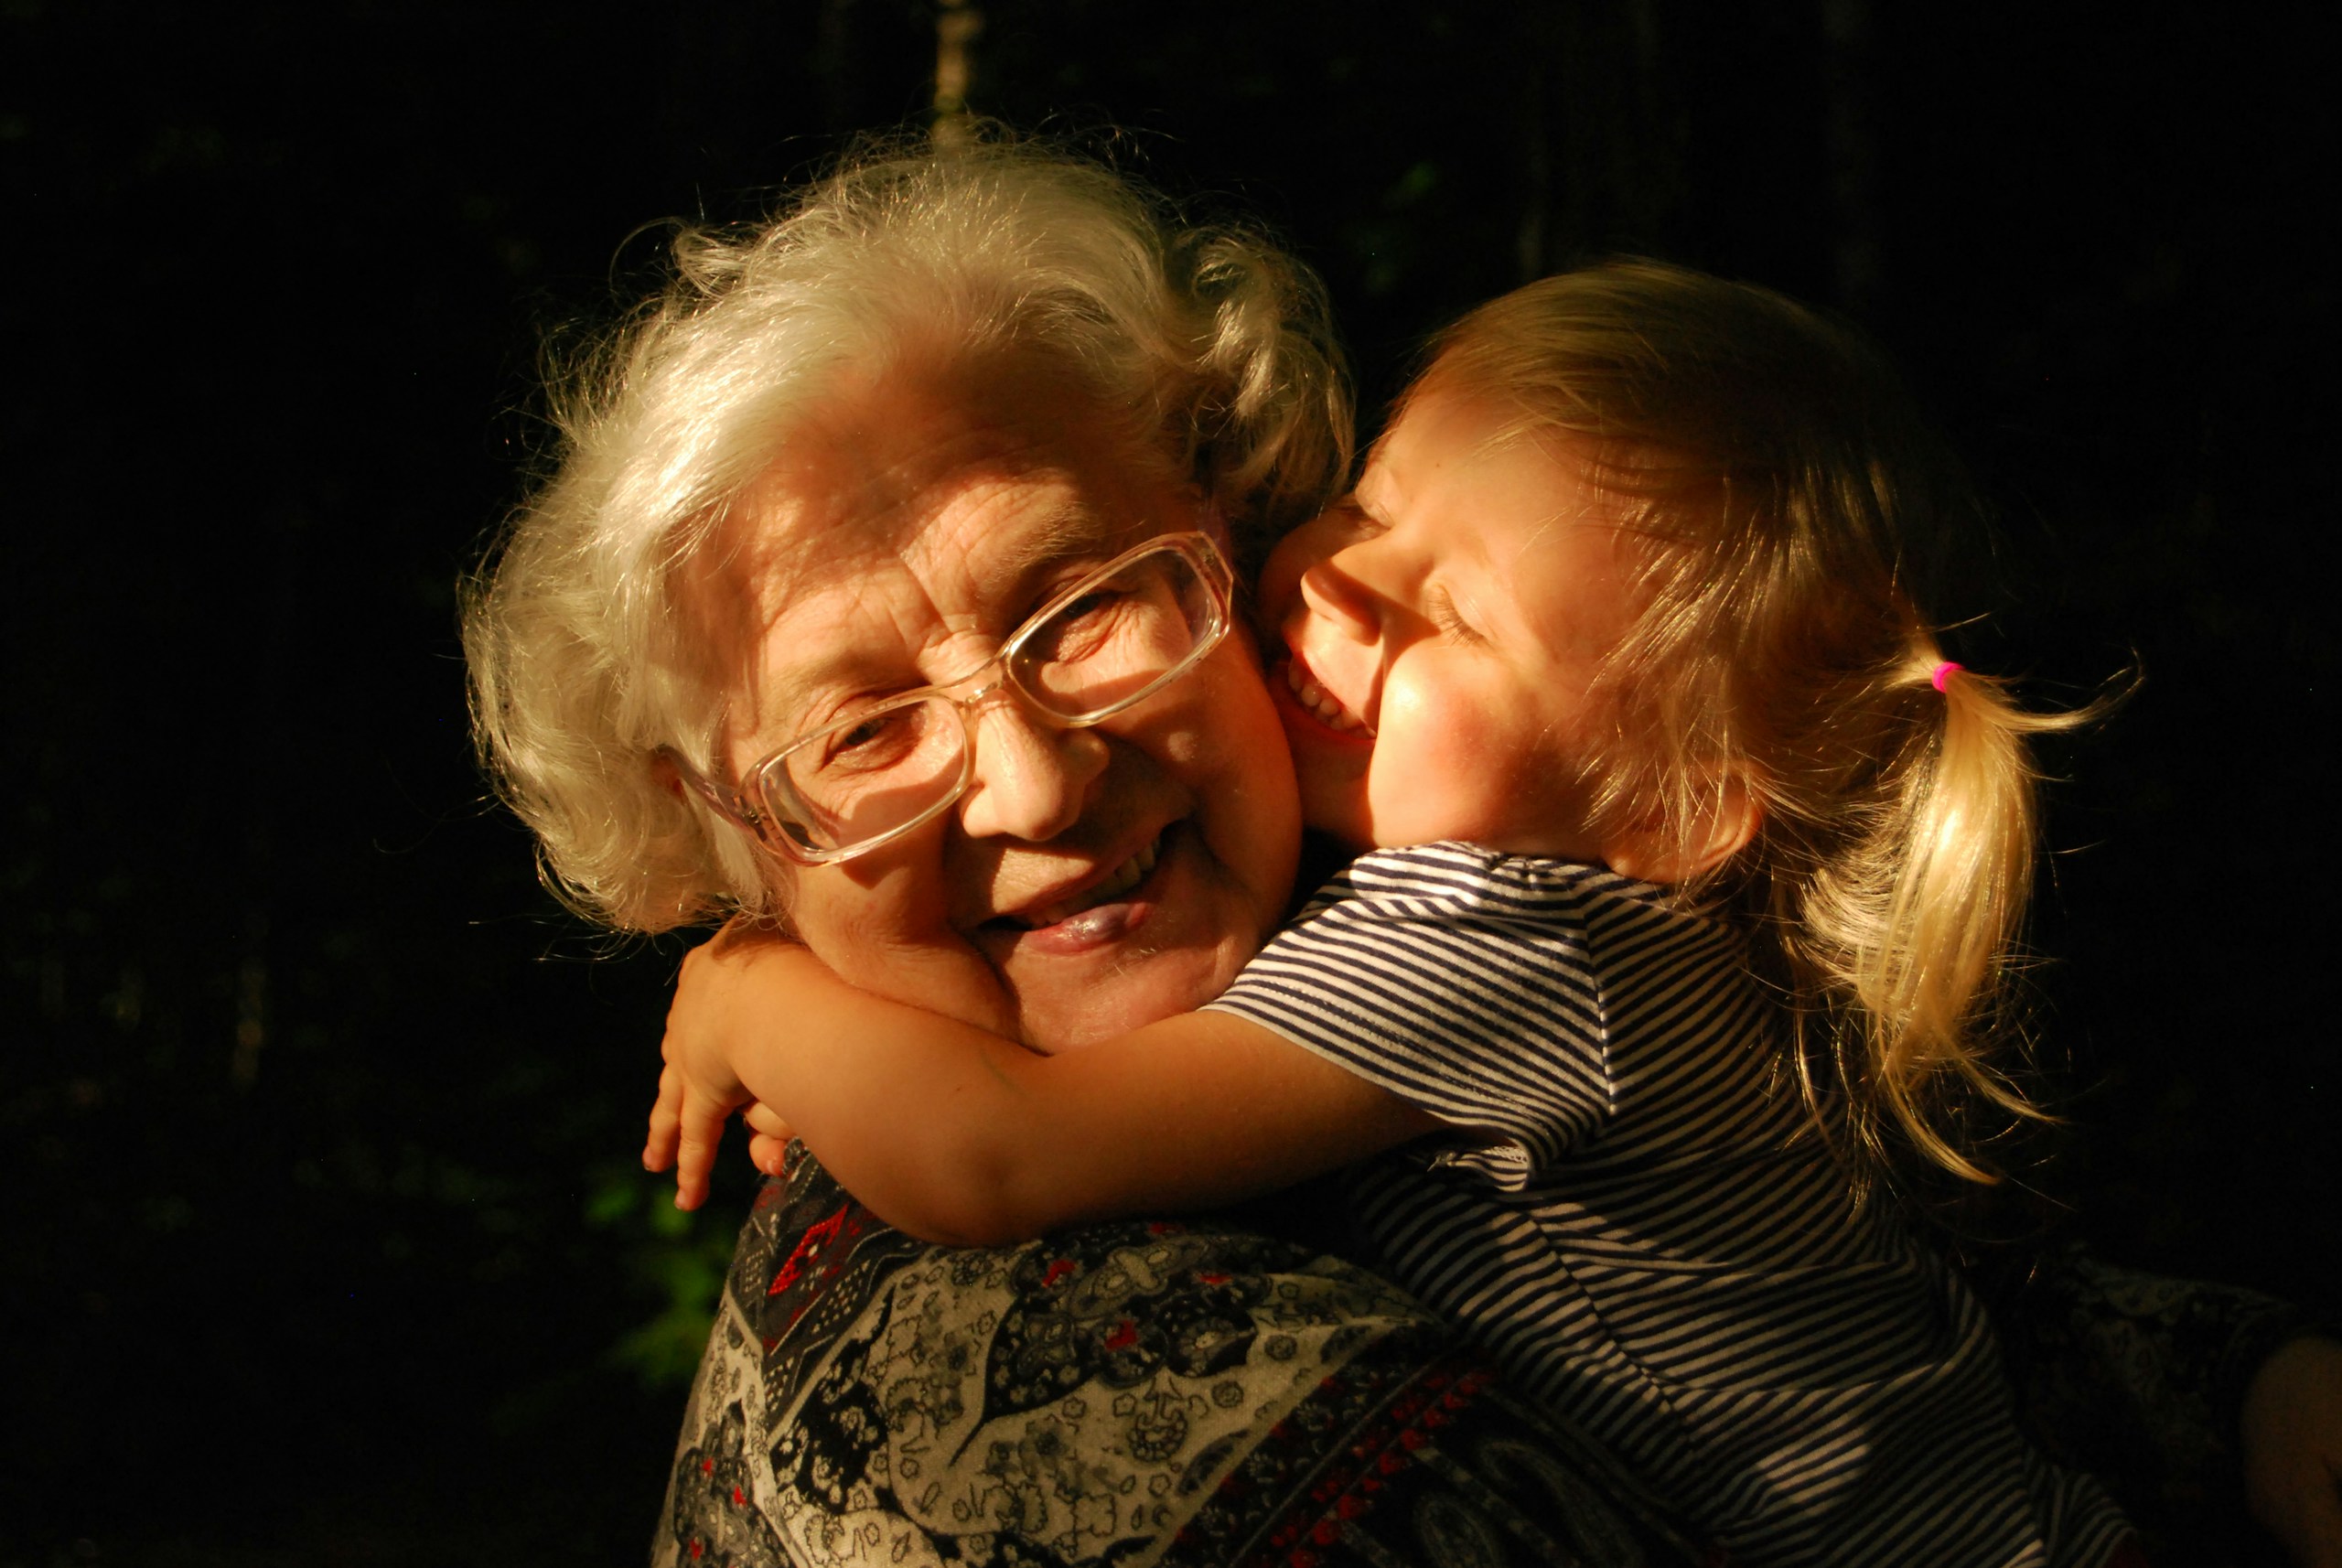
Grandmother hugging her young grandchild

What it is

Permanent protection with predictable growth.

Whole life insurance is permanent coverage designed to last your entire life, as long as premiums are paid. Your premium is set when the policy starts and generally stays the same.

Part of each premium builds cash value at a guaranteed rate defined in the contract. Some policies may also pay dividends, which are not guaranteed. Over time, you may be able to borrow against that cash value for needs like education or retirement.

Coverage designed to last your entire life
Fixed premiums that generally won’t increase
Cash value that grows at a guaranteed rate
Possible dividends (not guaranteed)

Key features

How whole life works for you

Six features that make whole life a trusted choice for families who want certainty.

Lifelong coverage

Protection that doesn’t expire after a set term, as long as premiums are paid.

Fixed premiums

Your premium is set at the start, so you can plan your budget with confidence.

Guaranteed cash value

Cash value grows at a guaranteed rate defined in your policy.

Dividend potential

Some policies may pay dividends, which are not guaranteed.

Access to cash value

Borrow against your cash value for future needs. Loans reduce the death benefit if not repaid.

Tax advantages

Cash value generally grows tax-deferred, and the death benefit is generally income-tax-free.

Benefits & considerations

The full picture, before you decide

Whole life offers certainty, but it costs more than term coverage. Here’s an honest look at both sides.

Benefits

Lifelong protection for the people who depend on you
Premiums that generally stay the same
Cash value with guaranteed growth
A generally income-tax-free benefit for your beneficiaries
Can be part of a legacy or estate plan

Things to consider

Premiums are higher than term life for the same coverage
Cash value grows slowly in the early years
Less flexibility to change premiums or coverage
Loans and withdrawals reduce the death benefit
Surrendering early may mean receiving less than you paid

Why it matters

Some promises should last a lifetime. Whole life coverage is built to be there for your family no matter when they need it.

FAQ

Whole life questions, answered

Still have questions? Book a free consultation and we’ll walk you through how whole life could fit your plans.
How is whole life different from term life?
Term life covers you for a set number of years and usually costs less. Whole life is designed to last your entire life and builds cash value, which is why premiums are higher.
Are dividends guaranteed?
No. Some whole life policies are eligible for dividends, but they are not guaranteed and depend on the company’s performance.
Can I borrow from my policy?
Yes. You can usually take a loan against your cash value. Loans accrue interest and, if not repaid, reduce the death benefit your family receives.
What happens if I stop paying premiums?
Depending on your policy, you may be able to use cash value to keep coverage in force, reduce your coverage, or surrender the policy. We’ll explain your options.
Is whole life a good way to leave an inheritance?
It can be. Because coverage is designed to last your lifetime, many families use whole life to leave a generally income-tax-free benefit to loved ones.

Create an account to access this functionality.
Discover the advantages